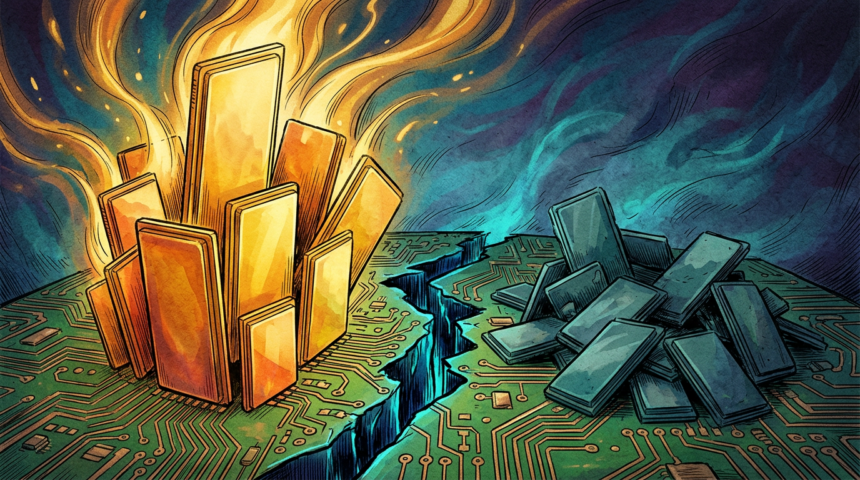
Two very different price curves are emerging inside the same memory category. TrendForce reports that high-capacity NOR flash is being bid up by AI servers while smaller-density parts lose momentum.
Devices of 256Mb and above are forecast to rise another 90 to 110 percent in the second half, and some could double. Contract prices in that segment already climbed 100 to 120 percent in the first half.
The low end is heading the other way. Mid and low-capacity parts should see gains narrow to 10 to 20 percent in the fourth quarter, as Chinese suppliers bring on more capacity.
Winbond stands to gain most, TrendForce says, as its 45nm line ramps to full production and delivers the industry’s largest bit growth this year. Macronix is more constrained, having prioritized NAND and eMMC capacity over NOR.
The demand pull looks structural rather than cyclical. An AI server carries three to five times the NOR flash of a conventional server, because boot code, firmware and retimer settings all need fast non-volatile storage near the board. Satellite and aerospace programs are adding to high-capacity demand from a different direction.
Suppliers cannot answer quickly. Even aggressive wafer expansion takes quarters to add bits, so TrendForce expects the imbalance to hold through the second half of 2026.